
6 Best Loss Run Processing Tools (2026)
By SortSpoke

Published May 19, 2026 | Updated October 14, 2026
Digital transformation in insurance has sat on carrier strategy decks for more than a decade. In 2026 the conversation has changed shape. The question is no longer whether to use AI. It's where AI agents actually pay off in property and casualty (P&C) operations, and where they quietly create new risk.
Most guides stay at altitude: cloud, customer experience, ecosystems. But if you run underwriting or claims at a commercial carrier, MGA or reinsurer, you know where the work piles up: in the inbox. Broker emails with twelve attachments. Loss runs from five prior carriers in five formats. A statement of values with 400 locations in a spreadsheet nobody designed for machines. That's the layer where transformation programs succeed or stall.
The pattern we see with carriers is consistent: the pilot impresses, then adoption plateaus and exceptions pile up. BCG's 2025 research on insurance AI found that only 7% of insurers surveyed had brought their AI systems to scale, while about two-thirds were still piloting.
This guide covers what digital transformation means for a P&C insurer in 2026, the trends driving it, a five-stage roadmap, where agentic AI fits next to human-in-the-loop design, how to modernize without replacing your core systems, and how to measure whether any of it is working.
Digital transformation in insurance is the redesign of how an insurer captures information, makes decisions and serves customers using modern technology such as cloud core systems, workflow automation, data and AI. For P&C carriers, it means moving submission intake, underwriting and claims from manual, document-heavy processes to governed, data-driven workflows.
The term has been stretched to cover everything from adding a chatbot to a claims page to rebuilding policy administration from scratch. A more useful working definition for an insurance operation: digital transformation is the redesign of decision flows, not the purchase of a platform. It's the deliberate restructuring of how information moves through your organization, how decisions get made, and who (or what) is accountable at each step. A platform is a tool. Transformation is what you do with it.
A platform purchase has a go-live date. A decision-flow redesign has an adoption curve, a governance model and a continuous improvement loop. The first is easier to sell internally. The second is much more likely to work.
In practice, P&C insurance digital transformation touches four layers of the operation:
Most transformation spending has gone to the systems and experience layers. Most of the operational drag still sits in intake and decision. (For a plain-language primer on the automation side, see our explainer on how insurance automation works.)
The key insurance technology trends for 2026 share one theme: AI is moving from isolated use cases into the core workflow, and regulators are moving with it.
Agentic AI refers to systems that can plan and execute multi-step tasks, calling tools, reading documents and taking actions, rather than answering a single prompt. In insurance, the first agentic use cases are orchestration: reading an inbound submission, classifying its documents, checking appetite, requesting missing information and preparing a file for an underwriter. The promise is real. So is the risk, which we cover in the agentic AI section below.
The generation of extraction technology matters. Template-based OCR broke on every new layout; earlier intelligent document processing (IDP) needed large training sets per document type. Large language models can now read non-standard loss runs, narrative engineering reports and broker emails with far less setup. The catch: LLMs can produce confident but wrong values, which is why source traceability and human verification have become buying criteria. Our overview of the evolution from OCR to IDP to LLMs walks through which approach fits which problem.
Carriers are increasingly unwilling to fund multi-year core replacements before seeing value. The 2026 pattern is to keep the system of record and embed new capability, such as document AI, triage scoring and data enrichment, inside the workbenches and core platforms teams already use.
Telematics in commercial auto, sensors in property and third-party data enrichment all give underwriters more signal. They also create more data to reconcile against what the broker submitted, which raises the value of clean, structured intake data.
In December 2023 the National Association of Insurance Commissioners adopted its model bulletin on the use of AI systems by insurers, which expects insurers to maintain a written AI systems program that covers governance, risk management and oversight of AI acquired from third-party vendors. For 2026 roadmaps, that means every AI deployment needs documentation, testing and an accountable human, including the ones a vendor runs for you.
With most carriers past their first pilots, the bottleneck has shifted from "can AI do this?" to "why hasn't this scaled?" We unpack the reasons in the trust gap behind stalled insurance AI pilots. The short version: governance, explainability and workflow fit, not model accuracy.
Two frameworks come up constantly. Both are useful for a carrier if they're applied to insurance work rather than left abstract.
A widely used model splits digital transformation into four types: process, business model, domain and cultural or organizational. Here's what each looks like at a P&C insurer:
| Type | What it means | What it looks like at a P&C carrier |
|---|---|---|
| Process | Redesigning how existing work gets done | Automating submission intake, loss run extraction and claims document handling, with human review on exceptions |
| Business model | Changing how the company creates and captures value | Usage-based commercial auto, embedded insurance at the point of sale, parametric covers |
| Domain | Moving into new markets or capabilities that technology opens up | Entering a specialty line or program business that was uneconomic to underwrite manually |
| Cultural / organizational | Changing skills, roles, incentives and how people work with technology | Redefining the underwriter role around judgment, building review teams, setting accountability for AI outputs |
Most P&C programs start with process transformation because it funds the rest; the cultural layer decides whether it sticks.
Here's a process-first version of the five stages, built for an underwriting and claims operation. Each stage depends on the one before it.
Start with the highest-volume, highest-friction document workflows. Submission intake and triage and loss run processing are almost always the right first move: high volume, well-defined enough to automate meaningfully, and measurable within weeks. Design the human review layer explicitly. Define what requires human sign-off and what can move forward on AI output alone.
Surface AI-extracted data inside the tools underwriters and adjusters already use to decide: risk summaries, loss trends, appetite fit. The human still makes the call. The AI eliminates the pre-work.
Push structured, reviewed data into policy administration, rating and claims systems through APIs and webhooks, so nobody re-keys what the AI already captured. This is the stage where "pilot" becomes "how we work."
Every human correction of an AI output is a training signal. Capture it, route it back into model improvement, and watch exception rates fall. This is what separates a static deployment from a learning system, and it's the most diagnostic of the signs your human-in-the-loop operation is working.
With reliable intake, decision support, integration and feedback in place, agents can safely orchestrate across the workflow: routing, appetite-based prioritization, follow-up requests, capacity management. Autonomy expands only where the data shows humans rarely override the system.
If the human-AI handoff is where transformation breaks down, document intake is where the breakdown usually begins. It's also the bottleneck that gets the least strategic attention relative to its impact. We examine the structural reasons in why insurance transformation stalls at intake; here's how it shows up across the commercial P&C workflow.
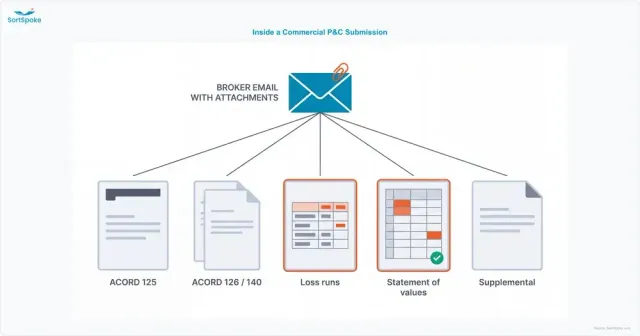
A commercial underwriting team receives far more submissions than it can quote competitively. Without automated submission triage, prioritization is informal: whoever landed in the inbox first, whoever followed up hardest. Automated intake splits the package, classifies each document, extracts the risk characteristics, runs clearance against existing accounts and scores the submission against appetite before an underwriter opens the file. The 2026 submission benchmarks quantify the gap between top-quartile and average teams on response time and quote-to-bind.
Loss runs are the data currency of commercial underwriting and one of the hardest documents to process consistently. Every carrier formats them differently, and multi-year histories need reconciliation. A commonly cited turnaround to obtain loss runs from prior carriers is 7–10 days; once they arrive, AI extraction turns them into structured claim records in minutes rather than hours of manual keying. If you need a refresher on the document itself, start with what a loss run report contains.
ACORD forms are standardized, which makes them sound easy. In practice they arrive as scanned PDFs, broker-filled variants and partial packets, and the 125, 126 and 140 stack differently by account. SortSpoke's internal benchmarks put manual ACORD 125 processing at 20–30 minutes per form versus under 2 minutes with automated extraction and review. Our breakdown of how the ACORD 125, 126 and 140 fit together covers what each form carries.
A statement of values (SOV) lists every insured location with its values, construction, occupancy and protection. SOVs arrive as spreadsheets with inconsistent columns and hundreds of rows, and property underwriters can't model catastrophe exposure until the data is clean; we cover the mechanics in statement of values standardization.
First notice of loss (FNOL) packets, police reports, repair estimates and medical records all need data extraction before a claim can be routed. This is where claims transformation is moving fastest: FNOL intake, document intake and low-complexity claims are increasingly automated, while adjusters keep the coverage and settlement decisions. SCM Insurance, for example, reported an 80% reduction in claims processing time with SortSpoke. Our guide to first notice of loss automation goes deeper.
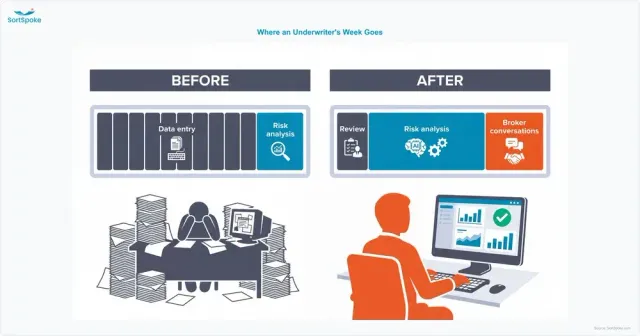
The opportunity cost is larger than the processing cost: every hour an experienced underwriter spends keying a loss run is an hour not spent on risk judgment. That matters more as senior underwriters retire, a dynamic we explore in how human-in-the-loop AI bridges the underwriting talent crisis. For an insurance-specific view of the technology itself, see our guide to intelligent document processing for insurance.
Agentic AI is the headline technology of 2026. An AI agent can chain dozens of steps: open the email, split the attachments, classify each document, extract fields, check appetite, draft a broker reply. That's exactly the multi-step work that clogs insurance operations, and exactly where errors compound.
Here's the math that rarely makes the vendor deck. A system that is 99% accurate per step is only about 82% reliable across 20 dependent steps (0.99 to the 20th power is roughly 0.818). A single commercial submission can involve twenty or more extraction, classification and routing steps. Per-step accuracy is the wrong metric. End-to-end reliability is what the business runs on, and the most dependable way to protect it is to break the compounding chain with human checkpoints.
Human-in-the-Loop AI (HITL)
Human-in-the-loop AI — a design pattern where AI systems handle data extraction, classification and pattern recognition, while human experts retain decision authority, review exceptions and provide feedback that continuously improves the model. The AI augments human judgment rather than replacing it.
In underwriting, that means the AI processes the submission, extracts the data, flags anomalies and surfaces what the underwriter needs. The underwriter makes the risk decision.
Human-in-the-loop design beats full autonomy in three situations that describe most of commercial insurance:
Trust is the other reason. SortSpoke's internal research found that only 16% of insurance professionals trust black-box AI decisions, rising to 60% when a human is in the loop. In a live poll of mutual insurers during a May 2026 NAMIC webinar led by SortSpoke, no respondents said they were all-in on autonomous AI, while 54% said they were scaling human-in-the-loop approaches.
Agentic AI vendors handle human oversight in four main ways, and they are not equivalent. Before you sign, find out which of these a vendor actually ships, and which it only describes:
| Oversight pattern | When a human sees the output | Risk if it's the only control |
|---|---|---|
| Confidence thresholds | Before release, but only for low-confidence predictions | Confidently wrong values pass straight through |
| Approval gates | Before any consequential action | Low, if the gate covers every external action |
| Source traceability | Whenever a reviewer checks a value | An enabler, not a control on its own |
| Sampling review | After release, on a sample | Errors reach downstream systems first |
Questions worth asking any vendor:
For reference, here's how SortSpoke answers those questions. No SortSpoke AI output is treated as final until a human reviewer accepts it. Each extracted value carries a 0–100 confidence score and a link to the exact page and region of the source document; the customer sets the auto-accept threshold; both the AI prediction and any human correction are retained; and AI can be switched off per project while review queues and audit trails keep working. While others promise autonomous AI decisions, SortSpoke keeps your team in control. Our human-in-the-loop approach explains the design in more detail, and the operational side is covered in four ways to staff a human-in-the-loop operation.
So where do AI agents actually pay off in P&C? In orchestration and preparation: assembling the file, chasing missing documents, pre-filling systems, prioritizing the queue. They pay off least, and carry the most risk, when they make consequential decisions unsupervised.
Before any deployment, ask how much friction it adds to your team's existing workflow. For most enterprise software, the honest answer is a lot: new logins, new interfaces, parallel workflows where the system of record and the system of intelligence don't talk. Adoption looks great in a self-selected pilot and disappoints at scale. We call this the embeddability problem, and it stalls more transformation initiatives than any other single factor.
Legacy core systems are deeply entrenched for good reason. Policy administration, claims and reinsurance systems carry years of institutional logic, regulatory compliance and data history. A transformation strategy that requires replacing them before AI can be deployed is a strategy that will wait for years. The more durable path is embedding intelligence into the existing stack rather than demanding the stack be rebuilt first.
The alternative to rip-and-replace isn't the status quo. It's a different design philosophy: document AI inside your existing workflow. No new portals. No new logins. In practice, modernizing underwriting workflows without replacing core systems uses a handful of integration patterns:
The difference in adoption is not marginal. When a tool requires no new login, no parallel workflow and no retraining of ingrained habits, adoption happens naturally instead of needing a mandate. By SortSpoke's internal estimate, embedded tools see 3–5x higher adoption than standalone portals. You can see what this looks like in an embedded underwriting workbench demo, and carriers weighing the approach can review SortSpoke's insurance automation for carriers.
The benefits of digital transformation in insurance show up as faster quotes, more submissions handled per underwriter, shorter claims cycles and fewer data errors. But you only get credit for them if you measure outcomes, not activity.
Here are the operating metrics that matter, with the benchmarks we can stand behind:
| Metric | What to measure | Benchmark |
|---|---|---|
| Time-to-quote | Submission received to quote delivered, by line and complexity tier | Baseline your own; faster response wins more business, as the first-responder advantage shows |
| Document processing time | Minutes from document arrival to reviewed, structured data | 85% faster (SortSpoke internal benchmark) |
| ACORD 125 handling | Time per application form | 20–30 min manual vs. under 2 min automated (SortSpoke internal benchmark) |
| Error rate | Share of extracted fields corrected downstream | ~4% manual to under 1% with human-in-the-loop review (SortSpoke internal benchmark) |
| Submissions per underwriter | Quoted submissions per underwriter per day or week | Baseline your own team before rollout, then track monthly |
| Overall underwriting efficiency | Output per underwriter hour across the workflow | 5x efficiency boost (Great American Custom Insurance) |
| Claims processing time | FNOL to routed, data-complete claim | 80% reduction (SCM Insurance) |
| Exception rate | Share of documents needing intervention beyond standard review | Should decline quarter over quarter; if it doesn't, the feedback loop is broken |
| Time to ROI | Months from contract to payback | Typically 6–12 months (SortSpoke customer data) |
Two softer measures deserve a place on the dashboard too. Human escalation patterns tell you where reviewers intervene most and why; the answers usually point to specific document types or brokers where the model or the review protocol needs work. Capacity utilization tells you whether underwriters are spending more of their week on complex, high-value submissions and less on data extraction. That shift is the core promise of AI-assisted underwriting, and it's measurable. Our underwriting efficiency calculator helps you benchmark where you stand today.
Real insurance digital transformation case studies tend to be narrower and more operational than the keynote versions. That's a feature. Here are three from SortSpoke customers, each starting at the document layer.
SCM Insurance reported an 80% reduction in claims processing time with SortSpoke. The pattern is typical of claims transformation in 2026: automate the extraction and routing of FNOL and supporting documents, and keep adjusters on coverage and settlement decisions.
Great American Custom Insurance, a specialty carrier, reported a 5x efficiency boost with SortSpoke. For specialty and excess lines, where submissions are non-standard and underwriter time is the scarcest resource, capacity is the transformation metric that matters most.
And at RGA, a global reinsurer, underwriting leadership put the value plainly:
"SortSpoke solves one of underwriting's messiest problems. Enables faster reviews, better risk assessment, greatly reduced manual effort."
— VP Underwriting, RGA
"Great accuracy levels achieved. Training was quick. SortSpoke stood out among competitors evaluated."
— Manager, Global Digital Underwriting, RGA
Notice what these examples have in common. None of these results required a core-system replacement or an autonomous agent. Each applied AI at the document layer, kept humans accountable for decisions and measured an operating outcome. Carriers looking for a structured way to evaluate vendors can use our insurer's guide to AI document extraction.
The challenges of digital transformation in the insurance industry are mostly not technical. They cluster into three groups.
Core systems built decades ago hold policy and claims history that can't simply be migrated, and integration work competes for the same scarce IT capacity as everything else. The practical response is sequencing: deliver value at the intake and decision layers first, through embedding and APIs, and modernize the core on its own timeline rather than making AI wait for it.
Experienced underwriters have good reasons to be skeptical of a new tool. Adoption fails when the tool adds steps, hides its reasoning or threatens their judgment. It succeeds when the tool removes drudgery, shows its sources and leaves the decision with them. Meanwhile, as experienced underwriters retire, carriers need to capture their judgment in workflows and review processes, a problem we cover in why the insurance talent crisis is really a knowledge crisis. Measure adoption alongside efficiency, because a tool no one uses is not a transformation.
Every new system that touches submission and claims data expands the attack surface and the compliance scope. AI adds a governance layer on top: model documentation, testing, drift monitoring and vendor oversight under frameworks like the NAIC model bulletin. Ask vendors for SOC 2 Type II reports, how data is isolated between customers, and how human oversight is documented. SortSpoke's approach is covered on our data security page.
P&C insurance digital transformation is the modernization of property and casualty operations, including submission intake, underwriting, policy administration and claims, using cloud systems, workflow automation, data and AI. In commercial lines it centers on turning unstructured documents such as ACORD forms, loss runs, statements of values and first notice of loss packets into reviewed, structured data that underwriters and adjusters can act on quickly.
The key insurance technology trends for 2026 are agentic AI moving from demos into pilots, large language models that can read unstructured insurance documents, embedded and API-first architecture instead of core-system replacement, more third-party, IoT and telematics data, and AI governance becoming a regulatory expectation under frameworks such as the NAIC model bulletin. The common thread is scaling AI beyond pilots with human oversight.
AI is unlikely to replace insurance jobs that depend on judgment, such as underwriting complex risks or settling disputed claims, but it is replacing much of the manual work inside those jobs. Data entry, document sorting and routine triage are increasingly automated. The underwriter role shifts toward risk judgment, broker relationships and reviewing AI outputs, which matters as experienced underwriters retire faster than new ones are trained.
Digital transformation at an insurance company is a multi-year program, but it should not take years to show value. A process-first approach can digitize high-volume document intake in the first three to six months, add decision support within a year, and expand to integrated, agent-assisted workflows in year two. SortSpoke customers typically see return on investment within six to twelve months.
Agentic AI vendors handle human-in-the-loop oversight through confidence thresholds that route uncertain predictions to human reviewers, approval gates before consequential actions, source traceability with audit logs, or after-the-fact sampling. These approaches differ sharply in risk. Buyers should confirm who sets the thresholds, whether any output is released before a human accepts it, and whether corrections are retained and used to improve the model.
An insurer should usually start digital transformation with high-volume document workflows such as submission intake, loss run extraction and claims document handling. These workflows are well defined, deliver measurable gains within weeks, and produce the clean structured data that later stages depend on, including decision support, core-system integration and AI agents. Starting with agents before the data layer is reliable tends to stall.
SortSpoke is insurance document AI with human oversight, built into the tools your team already uses. AI extracts the data. Your team makes the decisions. If you're deciding where document processing fits in your transformation roadmap, we'll show you on your own documents.
The 2026 Underwriting Efficiency Guide


